Why smart buyers welcome a slower Sydney market - John McGrath
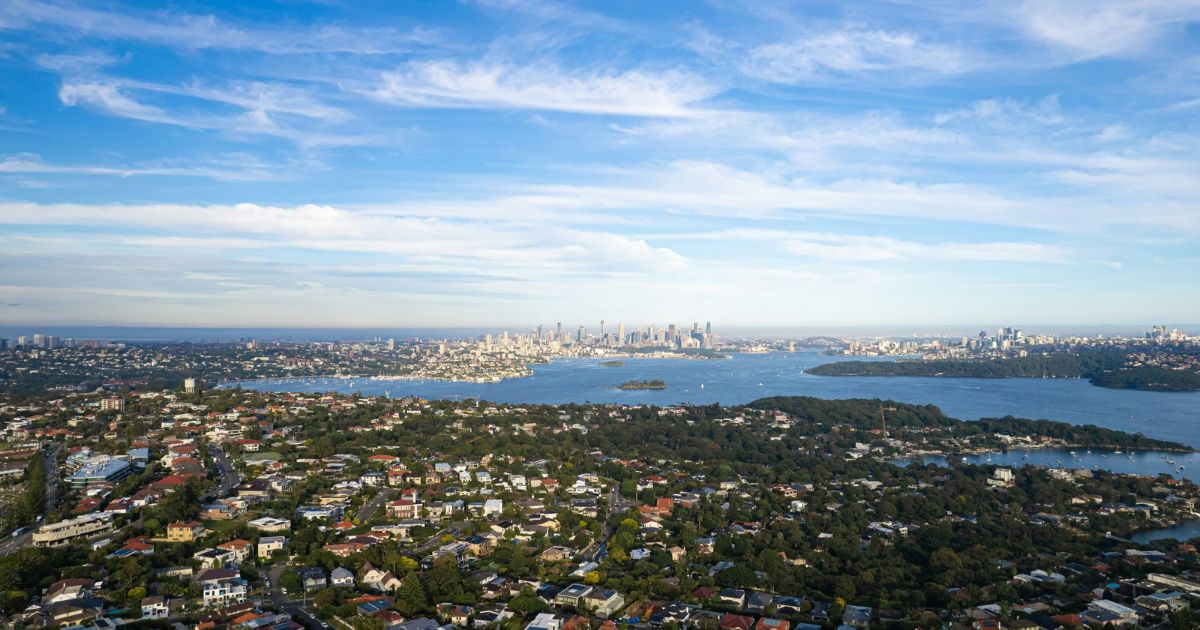
Sydney’s property market has undoubtedly softened this year due to the national market correction yet the city still offers plenty of opportunities for vendors and buyers.
But first, to the latest data from Cotality’s September Home Value Index report.
Sydney’s median dwelling price is just over $1.22 million, following a -7.1% drop from a peak level of $1,296,039 in February. This decline is above that of the 2022-2023 correction but the city’s median is still the highest in the country, second only to Brisbane’s $1.08 million figure.
Along with Brisbane and Perth, Sydney has recorded the country’s largest annual declines in transaction activity with estimated sales volumes down more than 20% compared with a year ago.
Sydney’s 2.2% vacancy rate is the highest of all mainland capital cities while house rents only increased by 5.3% in the past five years.
Meanwhile the city’s gross rental yield of 3.3% is the lowest in the country, which is a small improvement from the slight dips to 3% we saw across the past 12 months. These figures aren’t surprising for Sydney either with yields sitting around the 2%-3% point since 2016.
Looking at the overall property market, corrections like the current one generally only last about six to 12 months. As we’re more than half way through the downturn, this means we’re close to the bottom of the change.
It’s also been five months since the Federal Budget’s new policies were announced. So although consumer sentiment and confidence across the market is still low, investors have at least had some time to adjust to these changes.
Having said this, the Reserve Bank of Australia’s (RBA) rate rise last week resulted in a new cash rate of 4.6%. The increase was largely expected with all of the Big 4 Banks forecasting this change well in advance of the September meeting.
Either way, this is the highest rate we’ve seen since October 2011 and will impact buyer sentiment and confidence again.
But where we go from here will depend on interest rates. Each 0.25% increase in rates will likely impact the market by around 2%. If rates stabilise at these levels, I think we’ve just about reached the bottom of the market.
Price falls in Sydney of 12% to 15% are pretty common and for homes above $1.5 million, there are plenty of examples where sellers who need to sell have to accept offers 20% below expectations.
Yet supporting Sydney’s overall appeal for buyers is several new transport projects including Sydney Metro. Australia’s largest public transport project is already connecting the city’s western areas to the CBD with the latest Southwest section expected to open later this year.
Construction of the second stage of the Parramatta Light Rail linking Parramatta to Sydney Olympic Park is now underway as well.
Backing these positive factors, Sydney’s very different micro markets offer a diverse range of properties with demand for each market driven by distinctive supply and demand issues.
These differences are particularly apparent in the current slowdown as this has resulted in a sharp switch to a buyer’s market rather than a seller’s one.
The city’s ultra-prestige market in exclusive eastern suburb and north shore pockets continues to attract high demand and strong competition. At the other end of the market, the more affordable western regions are rapidly expanding in size and value thanks in part to the city’s new transport links.
The western suburbs are also often popular with families while some inner-ring locations also spill over into the western areas and offer a good variety of investor-held properties.
Most importantly for the city’s buyers and vendors right now, Sydney is traditionally the first market to recover from a downturn so 2027 should be a good year for the city.
By
John McGrath
October 5, 2026
2 min read
Share this Article